Homeowners policies do not cover “water damage” as one universal category. They evaluate the cause, timing, damaged property, exclusions, deductibles, and endorsements. Two wet kitchens can receive different coverage decisions because one resulted from a sudden connector failure and the other from a leak that continued for months.
Only the carrier and policy can determine coverage. The practical job for a homeowner is to protect the property and document the facts clearly.
General guidance cannot clear an unsafe property. Stay away from energized water, sewage, moving floodwater, and sagging materials.
Sudden and accidental releases
Many policies may cover resulting damage from a sudden, accidental plumbing or appliance release, subject to the policy. The failed pipe or appliance itself may be treated differently from the water damage it caused. Access required to reach a concealed pipe may also be handled under specific policy language.
Gradual leaks and maintenance
Damage associated with long-term seepage, deferred maintenance, deterioration, or repeated leakage may be excluded or limited. That is why discovery dates, photos, plumber findings, and prior repair records matter. Do not describe the cause beyond what is known; document observations and let the professionals diagnose it.
Flood, groundwater, and sewer backup
Standard homeowners coverage commonly distinguishes outside flooding or groundwater from an interior plumbing release. Separate flood insurance may apply to qualifying flood events. Sewer or drain backup may require an endorsement. Read the declarations and endorsements and ask the carrier direct questions.
Reasonable emergency mitigation
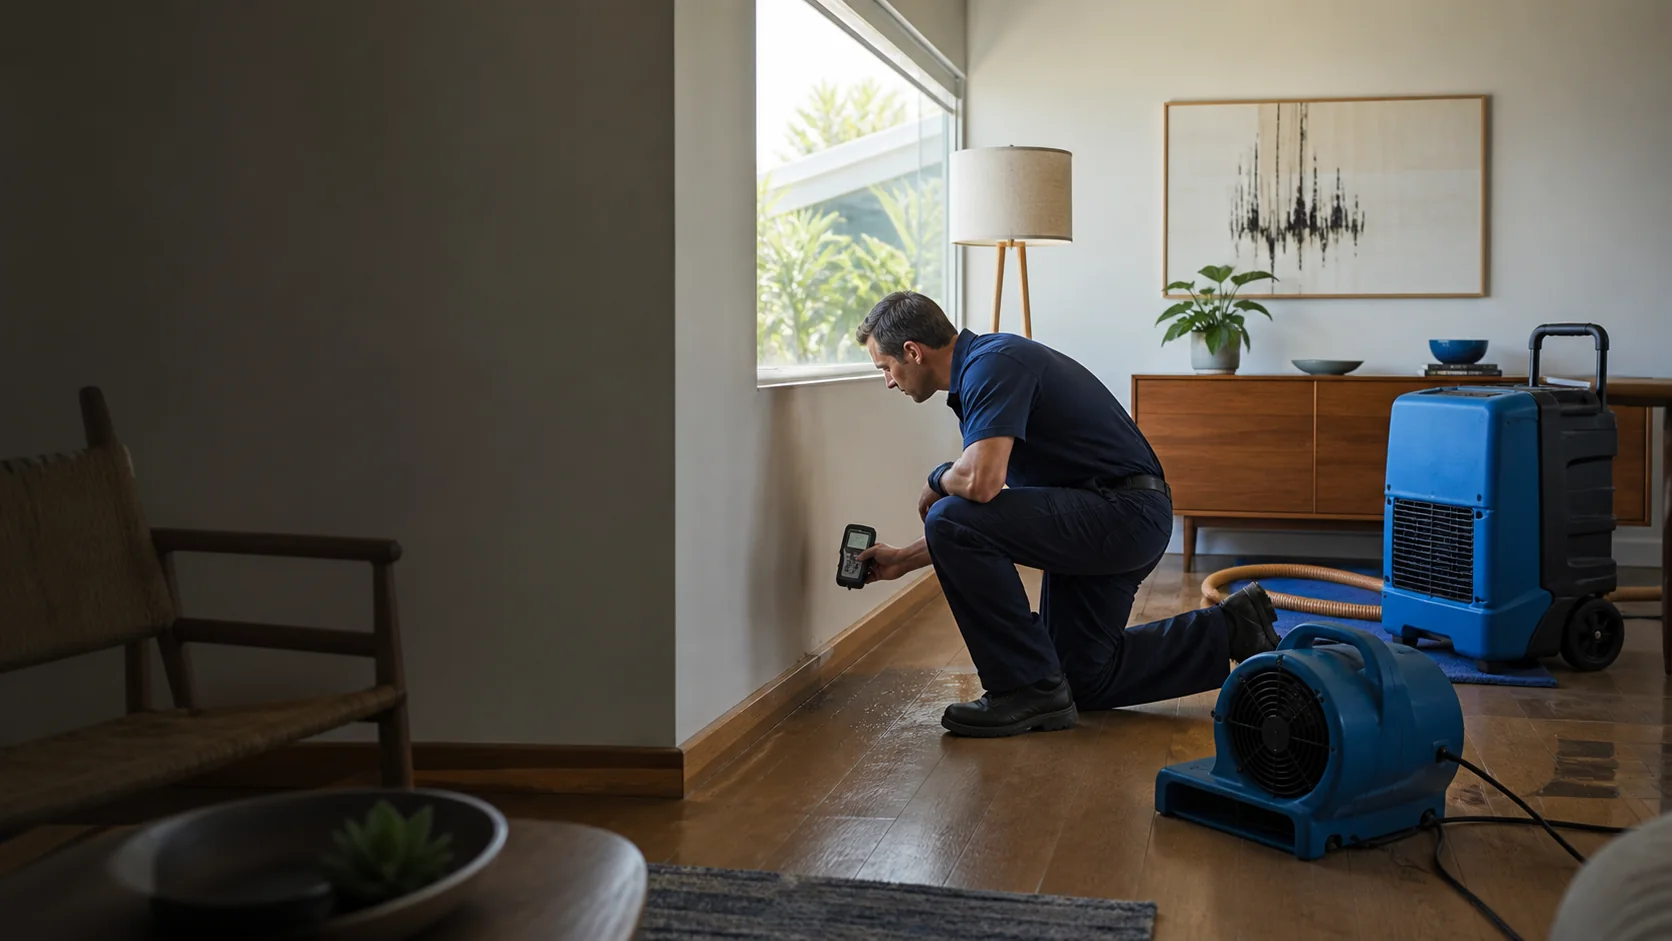
Policies generally expect owners to protect property from additional damage, but requirements vary. Take safe, reasonable steps such as stopping the source, extracting standing water, and preventing spread. Photograph first when possible and keep receipts, scopes, moisture logs, and removed parts.
- Claim number and adjuster contact
- Wide and close photos
- Timeline of discovery and shutoff
- Plumber, roofer, or drain diagnosis
- Restoration readings and invoices
- Contents inventory and receipts
Questions to ask the carrier
Ask whether emergency mitigation can begin, which deductible applies, whether sewer backup or mold has a sublimit, how temporary housing is handled, whether the policy pays replacement cost or actual cash value, and what documentation is required before damaged material is discarded.
How to apply this guide to a La Mesa property
The right response to does homeowners insurance cover water damage California begins with conditions at the building, not a generic checklist alone. Note whether the source is a pressurized supply, fixture or drain, water heater, appliance, roof, outside runoff, or an unknown pathway. Then record every room or level that may connect to it. A slab-on-grade Fletcher Hills home, a historic Rolando cottage, a Mt. Helix hillside property, and an apartment near Date Avenue may show the same stain for very different reasons. That building context determines which professional should stop the source and which finishes need closer moisture assessment.
When you request help, describe what changed and when: active flow, meter behavior, odor, warm flooring, material swelling, ceiling movement, recent rain, drain response, or a prior repair. Share whether electricity, sewage, tenants, customers, valuable contents, or limited access are involved. This allows the first conversation to focus on hazards and source control before equipment or repair decisions. For this topic, the most directly connected service paths are Water Restoration, Damage Repair, Sewage Cleanup. Each addresses a different phase, so ask who is responsible for source repair, mitigation, monitoring, cleaning, contents, and reconstruction.
Document the property before cleanup changes the scene. Take wide photographs, close views, and a short video that establishes the relationship between the source and affected rooms. Keep a timeline, receipts, removed parts, source-trade findings, moisture records, and written scopes. If insurance may be involved, report the event according to the policy and ask what the carrier needs before damaged material is discarded. A contractor can explain observed conditions and recommended work; only the carrier can interpret coverage.
Finally, use the repair phase to prevent a repeat. Confirm that plumbing, roofing, drainage, ventilation, or appliance corrections were tested before finishes close the assembly. Ask what measurements support dry-out, what materials were retained or removed and why, and how continuous flooring, cabinets, plaster, or historic finishes affect the repair boundary. Do not let uncertainty about coverage delay safe action that limits ongoing damage. Report the event promptly, stick to documented facts, keep an organized file, and ask the carrier to explain policy decisions in writing.
- Protect people before protecting finishes.
- Stop or isolate the source when that can be done safely.
- Map the water beyond the most visible mark.
- Separate emergency mitigation from permanent repair.
- Keep one organized record from discovery through closeout.
The bottom line
Do not let uncertainty about coverage delay safe action that limits ongoing damage. Report the event promptly, stick to documented facts, keep an organized file, and ask the carrier to explain policy decisions in writing.